Good news first: under the proposed Productivity Mega Deduction, used equipment can qualify for a 100% first-year write-off. The catch is who you buy it from.
Most immediate expensing rules in the past only applied to new equipment, or excluded used property in ways that made pre-owned machinery a poor tax choice. The Productivity Mega Deduction is different. Announced on September 15, 2026, it allows you to write off used equipment in full in the year you put it to use, as long as it passes one ownership test.
That test is easy to pass when you buy from a dealer or an unrelated seller. It is easy to fail when the seller is your own holding company, a family member's business, or you.
Draft rules, not yet law
The Mega Deduction was released as draft legislation on September 15, 2026 and can still change before it is passed. Ownership and arm's length questions are exactly where an accountant earns their fee. Use this article to spot the issues early, then confirm with them.
Can you write off used equipment? The rule in plain English
Under the draft legislation, used property qualifies for the Mega Deduction only if both of these are true:
- Neither you nor anyone you do not deal with at arm's length has owned it before. "Non-arm's length" includes related people and companies, and can include others who act in concert with you.
- It did not come to you through a tax-deferred rollover, such as the transfers commonly used in corporate reorganizations.
The asset also has to be acquired on or after September 15, 2026, and it cannot fall into one of the excluded classes, such as buildings or certain passenger vehicles.
Who counts as non-arm's length
Under the Income Tax Act, related persons are always treated as not dealing at arm's length. For most owner-managed businesses, that includes:
- Your spouse or common-law partner, your children, parents and siblings, and their spouses.
- A corporation you control, alone or with related people.
- Two corporations controlled by the same person or related group, such as an operating company and its sister company.
- Unrelated parties can also be non-arm's length as a question of fact, for example where one person directs both sides of the deal.
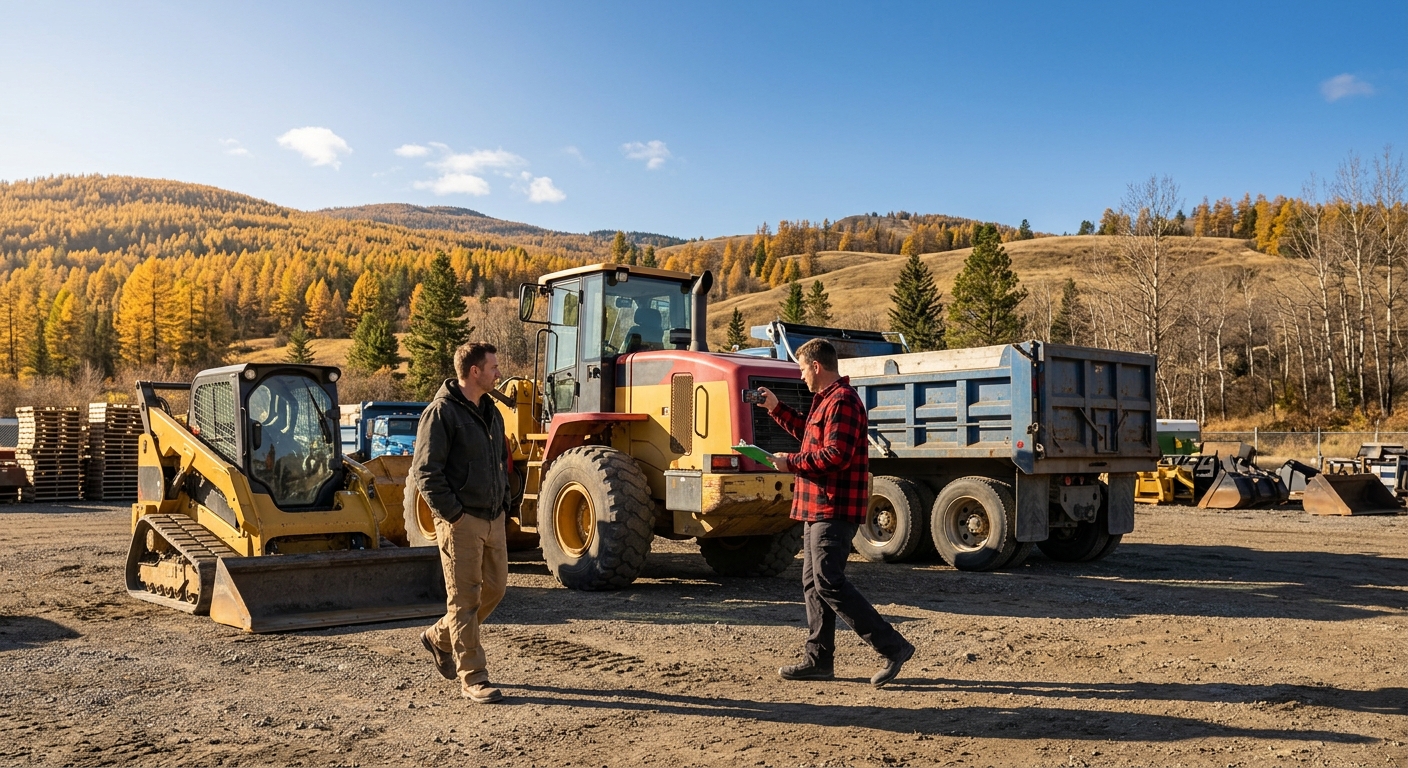
Six ways to fail the used equipment test
1. Buying from your own holding company or sister company
A common setup: the holding company owns the equipment and the operating company uses it. Moving the equipment between them is a non-arm's length transfer. The buyer will not get the Mega Deduction on it.
2. Buying from a family member's business
Your brother is retiring and selling you his excavator at a fair price. It may be a good deal, but because he is related to you, it is a non-arm's length purchase and does not qualify.
3. Reorganizing with a rollover
Transferring equipment into a new corporation on a tax-deferred basis is a normal planning step. The draft rules exclude property received this way, so a reorganization does not reset the clock for the Mega Deduction.
4. Buying back equipment you already owned
This catches people out with a sale and leaseback. Selling equipment to a leasing company and leasing it back is a sound way to release cash. If you buy that same equipment back at the end of the lease, though, you owned it before, so it will not qualify.
5. Buying a business through its shares
When you buy the shares of a company, the company keeps owning its equipment. Nothing new is acquired, so there is nothing new to write off. In an asset purchase from an unrelated seller, the equipment is newly acquired by you and can qualify. Goodwill in Class 14.1 is excluded either way.
6. Assuming a used vehicle qualifies
The draft rules exclude certain passenger vehicles in Classes 10 and 10.1, and previous use appears to be one of the tests. Confirm the treatment of any vehicle with your accountant. Heavy trucks and equipment usually sit in other classes, but confirm the class before you budget around the write-off.
Buying a business? Asset purchase vs share purchase
The Mega Deduction adds a new item to the negotiation when you buy a business. Sellers often prefer selling shares for their own tax reasons, including the lifetime capital gains exemption. Buyers now have a clearer reason to prefer buying assets: qualifying equipment bought from an unrelated seller can be written off in full in year one.
That makes the purchase price allocation matter more. How much of the price is allocated to equipment versus goodwill changes how much you can deduct right away. Your accountant and lawyer will negotiate that allocation. We arrange the financing to close it, including senior debt and mezzanine financing where the deal needs it. Lenders generally expect the buyer to bring meaningful equity to an acquisition.
Paperwork that protects the write-off
When you write off used equipment and your accountant or the CRA asks questions, you want to be able to show when you acquired the equipment, who you bought it from, and that you have never owned it before. Before you pay:
- Get a proper bill of sale with the seller's legal name, the date, the price, and serial or VIN numbers.
- Record the seller relationship. A note confirming the seller is an unrelated dealer or business is simple and useful.
- Keep delivery and in-service records, because the deduction lands in the year the equipment becomes available for use.
- Search for liens. In BC, a Personal Property Registry search shows whether a lender already has a claim on the equipment. Lenders run this anyway on private sales. Our used equipment financing guide has a full private-sale checklist.
Financing used equipment
Used equipment is very financeable, but lenders look at it differently from new. Expect questions about age, hours or kilometres, condition, and whether the seller is a dealer or a private party. Some lenders cap the age of equipment they will finance, and larger or older items may need an appraisal. Our guide to used equipment financing explains what lenders check and how terms change as equipment gets older.
This is where a broker helps. Lenders that will not look at a 12-year-old loader may be the wrong fit, while another lender in the same market finances that equipment every week. We work with 30+ lenders and match the asset to the lender that actually wants it. If you are deciding between owning and leasing, our guide to leasing vs financing equipment covers how each structure handles the Mega Deduction.
Used equipment write-off FAQ
Can you write off used equipment in Canada?
Under the proposed Productivity Mega Deduction, used equipment acquired on or after September 15, 2026 can be written off in full in the year it becomes available for use, as long as neither you nor a non-arm's length person owned it before and it was not acquired through a tax-deferred rollover. The measure is draft legislation and not yet law.
Can I buy equipment from my own holding company and claim the Mega Deduction?
Generally no. A holding company you control, or a sister company under common control, is not at arm's length with you. Equipment it previously owned does not meet the used property test, so the buyer cannot claim the Mega Deduction on that transfer.
Does equipment in a business I buy qualify for the Mega Deduction?
It depends on how you buy. In an asset purchase from an unrelated seller, the equipment is newly acquired by you and can qualify. In a share purchase, the company continues to own its equipment, so there is no new acquisition to write off. Goodwill is excluded in both cases.
What does non-arm's length mean for equipment purchases?
Non-arm's length parties include related persons, such as family members and corporations controlled by you or your family, as well as unrelated parties who in fact act together. Equipment previously owned by any of them does not qualify for the Mega Deduction when you acquire it.
Do used vehicles qualify for the Mega Deduction?
Some do not. The draft rules exclude certain passenger vehicles in Classes 10 and 10.1, and whether the vehicle was previously used appears to be part of that test. Heavy trucks and equipment often fall into other classes. Confirm the class of each vehicle with your accountant before relying on the write-off.
Can I finance used equipment through CBLE?
Yes. Canada Business Loan Experts arranges financing for used equipment from dealers and private sellers through a network of 30+ lenders. Lenders look at age, condition and the type of seller, so we match each asset to lenders that regularly finance that kind of equipment.
Financing for used equipment, matched to the right lender
Dealer or private sale, new to you or new to the market. 30+ lenders, all credit profiles considered. No obligation.
Would rather talk it through first? Call (604) 762 7350 or book a call.
Not tax advice. The Productivity Mega Deduction is draft legislation as of the publication date and may change. Confirm the treatment of any purchase with a licensed accountant.