A purchase order signed on December 30 does not get you the 2026 write-off. A machine that is installed and running on December 30 can.
If you are planning a year-end equipment purchase, the proposed Productivity Mega Deduction raises the stakes. Qualifying equipment acquired on or after September 15, 2026 can be written off in full in the tax year it becomes available for use. Get the timing right and the entire cost comes off this year's taxable income. Miss it by a week and that deduction moves to next year.
The timing is not set by when you sign, when you pay a deposit, or when the invoice is dated. It is set by when the equipment is ready to work. For businesses with a December 31 year-end, that leaves about twelve weeks from early October, and holiday slowdowns at suppliers, installers and lenders eat into it.
Draft legislation and your own situation
The Mega Deduction is draft legislation released on September 15, 2026 and is not yet law. Whether a purchase makes sense this year depends on your income, your tax rate and your plans. Confirm with your accountant before you buy anything for tax reasons.
The two dates that decide your write-off
Date 1: When you acquire it
The equipment must be acquired on or after September 15, 2026 to qualify for the Mega Deduction. Acquisition generally means when you get ownership, which usually happens when title passes or delivery is complete, not when you sign an order or pay a deposit. Equipment you already acquired before September 15 stays under the old rules, even if it goes into service later. If a purchase straddles September 15, ask your accountant when ownership actually transferred.
Date 2: When it becomes available for use
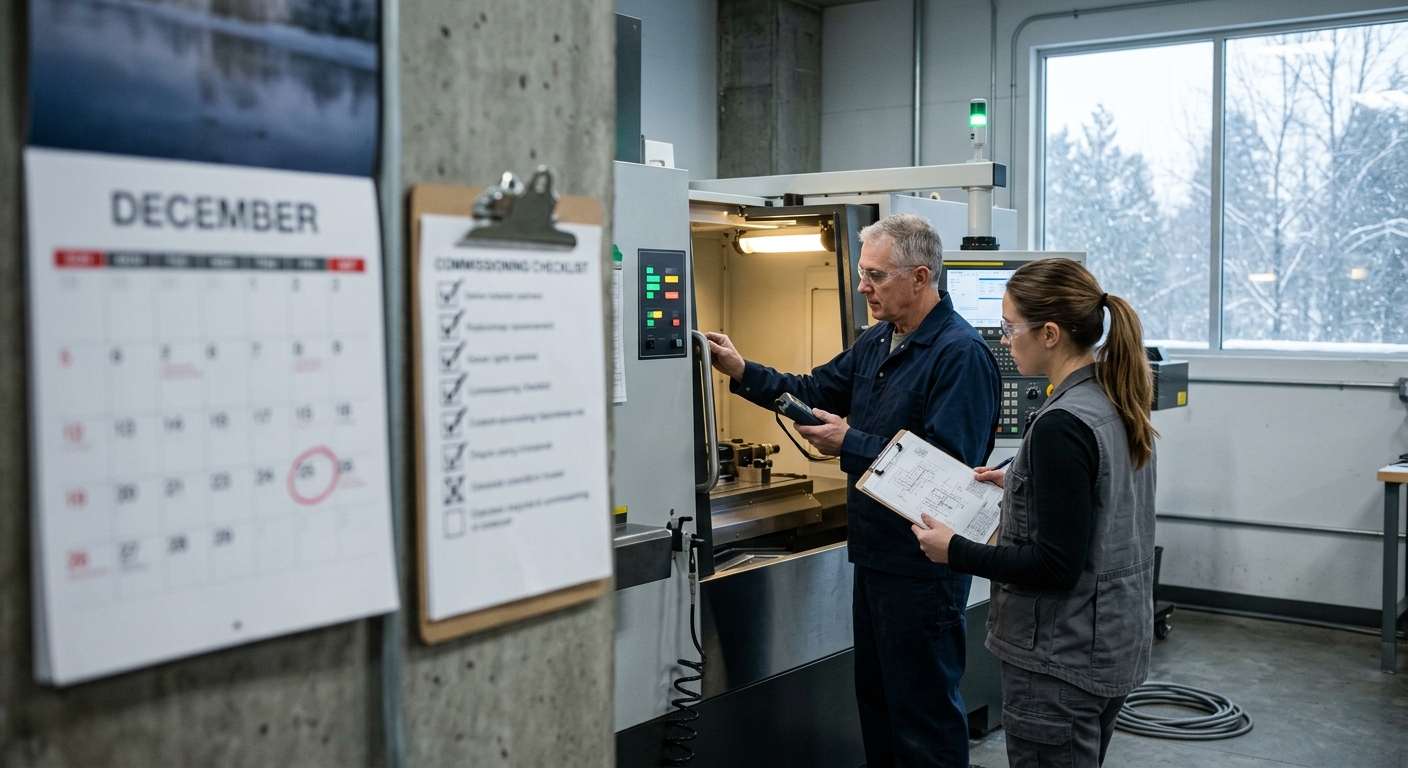
The deduction is claimed in the tax year the equipment becomes available for use. Under the CCA "available for use" rules, that is generally when you first use it to earn income, or when it has been delivered and is capable of doing the job it was bought for. A crated machine waiting for an electrician is not yet available for use.
Both dates have to line up inside the same tax year for the deduction to land in that year. If the equipment is acquired in December but not working until January, the deduction belongs to next year.
Work backwards from your year-end
Here is a practical timeline for a business with a December 31 year-end. If your fiscal year ends on another date, as many corporations' do, shift it to match.
| When | What to do |
|---|---|
| Early October | Choose the equipment and get supplier quotes with real delivery dates. Ask your accountant to confirm the CCA class and whether the purchase makes sense this year. |
| Mid October | Apply for financing. A straightforward file can be approved in days. Larger, used or specialized equipment can take a few weeks. |
| Late October to November | Approve the financing, place the order, and book delivery and installation. |
| November to early December | Take delivery, install and commission. Leave a buffer for parts, inspections and training. |
| Before December 31 | Equipment working, or ready to work. Keep the bill of sale, delivery record and in-service date on file. |
Imported or custom equipment can have lead times of months, not weeks. If that is your situation, the realistic target may be next year's year-end, and you can plan for it now.
Should you make a year-end equipment purchase just to save tax?
Usually not, if you do not need the equipment. The Mega Deduction changes when you deduct the cost, not how much you deduct in total. Spending $150,000 to save tax on $150,000 still leaves you $150,000 lighter, minus the tax saving. The right reason to buy is that the equipment earns its keep. The tax timing is a bonus on a decision that already makes sense.
There are also cases where waiting can be better:
- Your income is lower this year than next. A deduction is worth more against income taxed at a higher rate. A corporation expecting to move from the small business rate to the general rate next year may get more value by putting equipment into service next year. Your accountant can run both scenarios.
- You are not incorporated. Individuals and partnerships with individual members cannot use the Mega Deduction to create or increase a loss. Any unused amount carries forward in your CCA pool, but the immediate benefit is limited by this year's income.
- The rules are still draft. If the final legislation changes, purchases made purely for the deduction carry more risk than purchases you needed anyway.
Paying for it without draining year-end cash
Year-end is when many businesses are also covering holiday payroll, inventory and tax instalments. Paying cash for equipment in December can squeeze all of that at once. Financing lets you put the equipment to work before year-end and pay for it over its useful life.
A quick example
A $150,000 machine financed over 60 months at an illustrative 9% works out to about $3,114 a month. If it is in service by year-end and qualifies, the full $150,000 can be deducted this year, while you have paid only a payment or two. The 9% rate is for illustration only. Actual terms depend on the asset, your business and the lender.
If you expect a large refund or lower tax instalments because of the deduction, the CAPEX Accelerator, a 6 to 18 month bridge with flexible prepayment, lets you buy now and pay down quickly once the tax saving arrives. For longer-life assets, a standard equipment loan matched to the useful life usually fits better. If you are weighing a lease, remember that with a true lease the lessor, not you, claims the Mega Deduction. Our guide to leasing vs financing equipment explains why.
Get a rough payment in two minutes with our equipment lease payment calculator, then talk to us about structure. For short-term options, see bridge financing.
Year-end equipment checklist
- Confirm your fiscal year-end date.
- Confirm the CCA class of each asset with your accountant, especially vehicles.
- If buying used, confirm the seller is at arm's length. See our guide to writing off used equipment.
- Get delivery and installation dates in writing from the supplier.
- Apply for financing early enough to allow for lender review and documents.
- Keep the bill of sale, delivery record and the date the equipment went into service.
- Check the status of the Mega Deduction legislation with your accountant before you file.
Year-end equipment purchase FAQ
When does equipment have to be in use to claim the 2026 write-off?
The Mega Deduction is claimed in the tax year the equipment becomes available for use. That generally means it has been delivered and is being used to earn income, or is capable of doing the job it was bought for, before your fiscal year-end. A signed order or deposit alone is not enough.
Does a deposit or purchase order before year-end count?
No. A deposit or purchase order does not make equipment available for use, and usually does not mean you have acquired it yet. The deduction depends on the equipment being acquired and ready to work within the tax year.
What if I bought the equipment before September 15, 2026?
Equipment acquired before September 15, 2026 does not qualify for the Productivity Mega Deduction, even if it goes into service afterwards. It stays under the previous capital cost allowance rules, which may still include enhanced first-year treatment. If a purchase straddles the date, ask your accountant when ownership actually transferred.
Should I buy equipment before year-end to reduce my taxes?
Only if you need the equipment. The Mega Deduction speeds up when you deduct the cost but does not increase the total deduction. In some cases, such as when your income will be taxed at a higher rate next year, waiting can be worth more. Your accountant can compare both years for you.
How long does equipment financing take?
A straightforward equipment financing file can be approved within a few business days once documents are in. Larger amounts, used or specialized equipment, and businesses with more complex finances can take a few weeks. Applying in October or early November leaves time before a December 31 year-end.
My fiscal year-end is not December 31. Does this still apply?
Yes. The deduction follows your own tax year, not the calendar year. A corporation with a March 31 or June 30 year-end has until that date to have qualifying equipment acquired and available for use for the deduction to fall in that year.
Get the equipment working before year-end
Fast approvals for straightforward files. Loans, leases and short-term bridges from 30+ lenders. No obligation.
Would rather talk it through first? Call (604) 762 7350 or book a call.
Not tax advice. The Productivity Mega Deduction is draft legislation as of the publication date and may change. Confirm the treatment of any purchase with a licensed accountant.